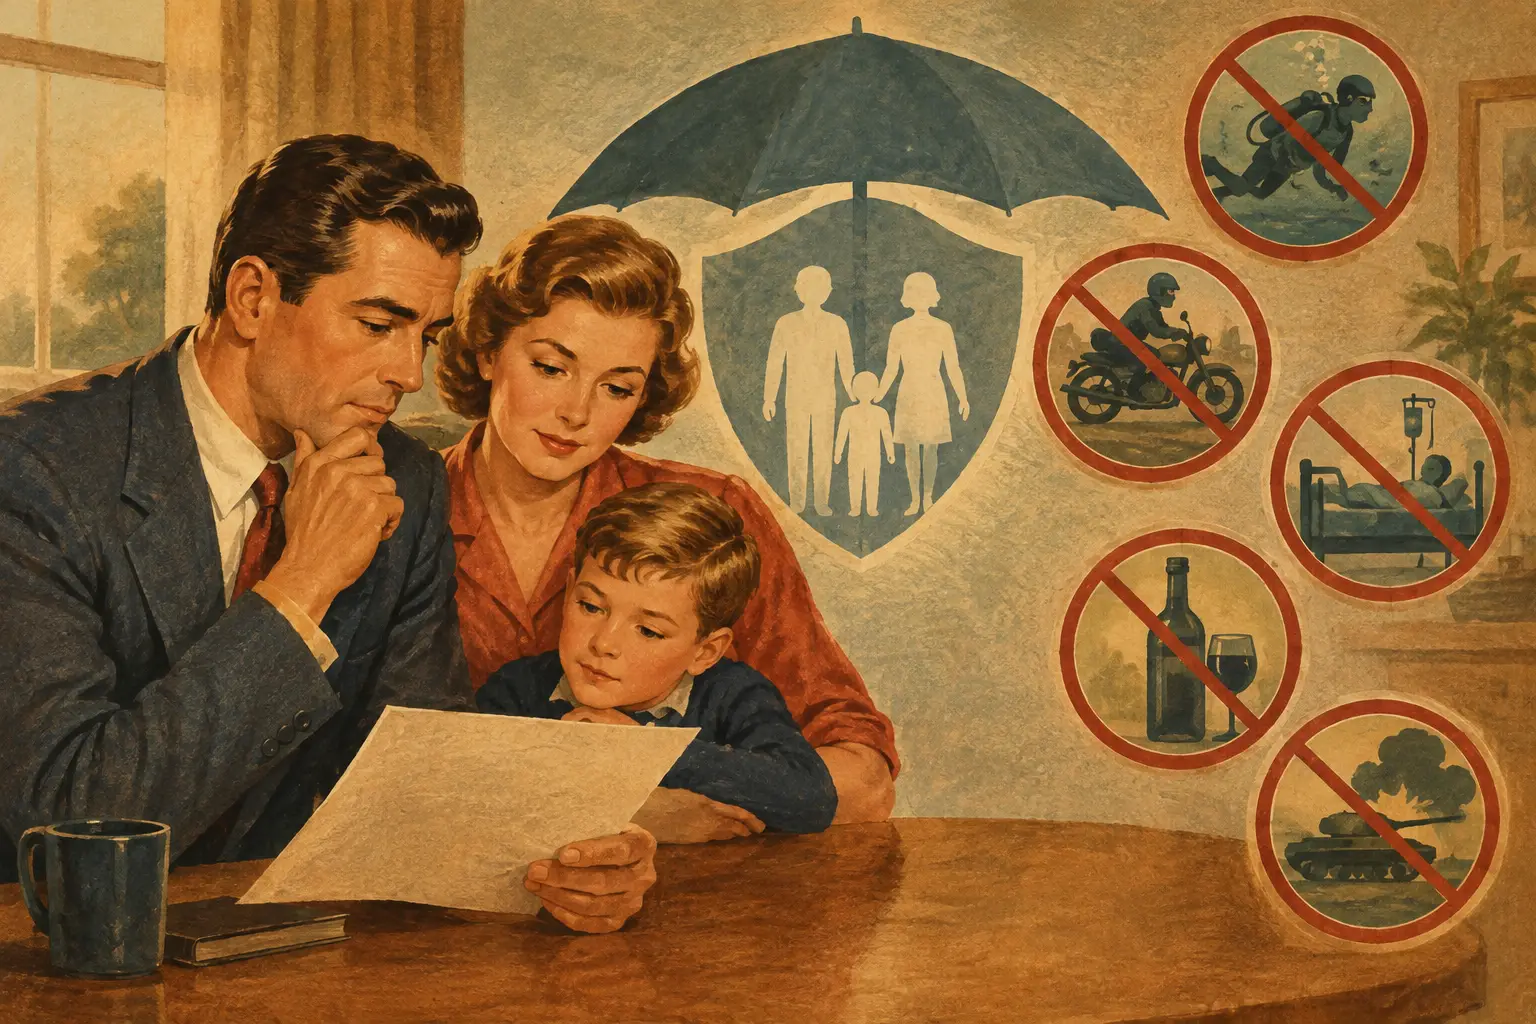
A life insurance policy is meant to be there when your family cannot afford another financial problem. That is why life insurance exclusions deserve more attention than the monthly premium or the headline coverage amount. An exclusion is a circumstance the contract does not cover, or covers only after specific conditions have been met. If you apply without understanding those limits, you may leave a gap in the very protection you are counting on.
For many applicants, the bigger risk is not that exclusions exist. Most life insurance contracts have them. The risk is assuming every carrier handles the same facts, activities, and application disclosures the same way. They do not. A strategic review before you apply can help you pursue coverage that fits your actual life instead of a policy built around assumptions.
What Life Insurance Exclusions Actually Mean
An exclusion is contractual language that limits the insurer's obligation to pay a death benefit under certain circumstances. The exact wording matters. It is not enough to hear that a policy "covers death from any cause" and stop there. Coverage may still be subject to exclusions, a contestability period, policy requirements, and the information provided during underwriting.
Some exclusions are relatively standard across the industry. Others are tied to the policy type, rider, applicant profile, or the carrier's underwriting decision. A carrier may issue a policy with an added exclusion because of a hazardous occupation, aviation activity, foreign travel pattern, or recreational pursuit. Another carrier may be willing to consider the same risk without that specific limitation, though the coverage class, underwriting requirements, or available policy design may differ.
This is why a quote alone is not a coverage strategy. The application, underwriting file, and final policy contract all matter.
The Most Common Life Insurance Exclusions
Suicide during the early policy period
Most life insurance policies contain a suicide provision for an initial period, commonly two years, although contract terms and state rules control. If death occurs by suicide within that period, the insurer may limit its payment, often to premiums paid rather than the full death benefit.
This provision should never be treated as a reason to avoid coverage. It is a standard policy condition that underscores why accurate disclosure and careful policy review matter from day one.
Material misrepresentation or fraud
This is the exclusion-like issue that creates the most preventable problems. If an application contains material omissions or inaccurate answers, the insurer may investigate whether the information affected its underwriting decision. A death claim during the contestability period can trigger close review of medical records, prescription history, motor vehicle records, financial information, prior insurance activity, and other application data.
The key word is material. Not every innocent mistake leads to a denied claim. But an undisclosed condition, tobacco use, risky driving history, hazardous activity, or prior coverage issue can matter if it would have changed the carrier's decision or terms.
Do not let a rushed online form turn a complicated history into an inaccurate answer. "No" is not a strategy when the correct answer requires context. The better approach is to identify what the carrier is likely to see, determine how it should be presented, and apply where that profile has a reasonable fit.
Dangerous activities and aviation
Some policies exclude or restrict deaths connected to certain high-risk activities. Private aviation, skydiving, technical climbing, scuba diving, racing, and similar pursuits can receive special scrutiny. The issue is often not whether you have ever tried an activity. Underwriters typically care about frequency, training, depth or altitude, location, purpose, and whether the activity is planned or ongoing.
A policy may be issued with an aviation or hazardous-avocation exclusion, especially when the carrier is unwilling to take the risk on standard terms. That can be acceptable in limited situations, but it should be a conscious decision. If flying or a particular activity is a meaningful part of your work or lifestyle, an exclusion can materially reduce the value of the policy.
War, terrorism, travel, and foreign residence
Many people assume travel automatically voids life insurance. Usually, that is too broad. Ordinary travel may have no impact at all. The concern rises when travel involves high-risk regions, repeated international assignments, active conflict areas, or a change in residence outside the United States.
Some contracts contain war-related limitations. Others may not use a broad exclusion but will examine travel and residence closely before issuing a policy. The practical point is simple: disclose planned travel and overseas connections before submitting an application. Do not wait until after the policy is issued to learn that your expected travel creates a problem.
Illegal acts and policy conditions
Certain policies may limit coverage for death connected to criminal activity or other prohibited conduct. Contract language varies, so this is not an area for assumptions. In addition, a policy can lapse if required premiums are not paid after any applicable grace period. A lapsed policy is not an exclusion, but the result for a family can be just as severe: no active death benefit when it is needed.
Set up dependable payment arrangements, keep beneficiary information current, and store the policy where a trusted person can find it. Coverage only protects your family if it remains in force and they know it exists.
Exclusions Are Not the Same as Underwriting Decisions
Applicants often mix up exclusions, declines, rated policies, and contestability. They are different issues, and the distinction affects how you should apply.
A decline means the carrier will not issue the requested policy based on its guidelines. A rating or table class means it may issue coverage with different pricing because it accepts the risk on modified terms. An exclusion means the carrier may issue the policy but carve out a particular cause or circumstance of death. Contestability is an initial period during which the insurer may investigate the accuracy of application statements if a claim occurs.
These outcomes are not interchangeable. A carrier that considers an exclusion may still be the wrong fit if the excluded activity is central to your life. Conversely, an applicant who assumes a decline is inevitable may have options with a different carrier if the file is properly understood before submission.
That is particularly relevant for people with health histories, prescription use, sleep concerns, anxiety, tobacco use, weight changes, driving violations, financial complexity, or prior application issues. The goal is not to hide information. It is to avoid placing a valid but nuanced profile in front of the wrong underwriting system first.
What to Review Before You Accept a Policy
Read the final policy, not just the illustration or initial quote. Focus on the insuring agreement, exclusions, riders, premium schedule, lapse provisions, and any endorsements attached to the contract. An endorsement can modify the base policy, and it deserves the same attention as the main document.
If you have a business, fly privately, travel frequently, participate in a higher-risk sport, or expect major lifestyle changes, ask direct questions before accepting coverage. Does the contract contain a specific exclusion? Does it apply to every death connected to the activity or only certain circumstances? Is it permanent? Could another policy structure or carrier better align with your needs?
Also confirm the basic facts: the insured person's name, coverage amount, policy owner, beneficiaries, and payment method. A policy can be medically approved and still be poorly arranged if ownership and beneficiary designations do not support the purpose of the coverage.
Why Applying in the Right Order Matters
Every formal application creates a record. Depending on the carrier and the information involved, medical exams, prescription checks, prior application responses, and other reports may influence future underwriting. Applying broadly because an online form takes ten minutes can create complications that a short pre-screening conversation might have avoided.
Before a formal application, clarify the facts that could affect both approval and policy terms. That includes your health background, medications, height and weight, driving record, nicotine use, occupation, travel, hobbies, existing coverage, and prior insurance decisions. Then match those facts to a carrier likely to assess them fairly.
This is not about finding a loophole. It is about choosing an underwriting path that gives complete information the proper context. For applicants who need meaningful coverage to protect a mortgage, income, business obligations, or an estate plan, that preparation can be the difference between a clean policy and a policy with limitations that were never fully considered.
A life insurance exclusion is not automatically a reason to walk away. It is a reason to slow down, read the contract, and make sure the protection you buy still protects the life your family actually lives.